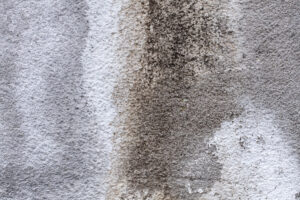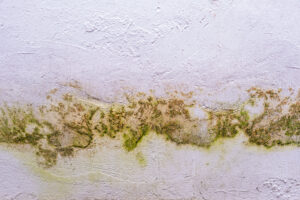


The moment you move into a newly purchased property and discover damp that was not disclosed, not visible at viewing, or dismissed as minor in the survey — the initial response is typically a mixture of panic, anger, and a feeling of helplessness. You have just spent tens or hundreds of thousands of pounds on a property, and it has a problem that was either hidden from you or that no one caught.
The reality is that your options are more substantial than they might initially appear. Depending on how the damp was missed or concealed, you may have legal recourse against the seller, a claim against your surveyor, or a buildings insurance claim to pursue — alongside the practical programme of actually getting the property dried out and restored. This guide covers all of these options clearly.
Step 1 — Document Everything Immediately
Before you have any conversation with a solicitor, your surveyor, or your insurer, document what you have found.
- Photograph and video every affected area with timestamps
- Note the location, height, and pattern of any visible damp or mould
- Note any fresh redecoration you discover has been applied over affected areas — paint that is bubbling, cracking, or showing staining through, or areas that appear newly painted in isolation from the rest of the room
- Keep all the survey report, the seller’s Property Information Form, and any pre-exchange correspondence
This contemporaneous evidence is what makes or breaks any subsequent legal or insurance claim. The evidence of what you found and when you found it is far more valuable than any retrospective assessment.
Step 2 — Commission a Professional Moisture Survey
The first professional appointment should be with a BDMA-certified moisture surveyor — not a solicitor, not a contractor, not a damp-proofing company offering a free assessment. A professional BDMA survey:
- Uses calibrated instruments and thermal imaging to map moisture systematically across all affected surfaces
- Produces a written report with specific readings, probable cause identification, and remediation recommendations
- Establishes the baseline evidence of the extent and likely duration of the problem
This survey report is the evidence document that underpins every subsequent step — the legal claim, the insurance notification, and the remediation brief. Without it, you are asserting that there is damp without the documented evidence that a professional claim or legal case requires.
The cost — typically £300 to £600 — is the most important single expenditure you can make in the immediate aftermath of discovering damp in a newly purchased property.
Read also- hidden water damage when buying a house UK
Step 3 — Identify Your Legal Options
Depending on the circumstances of your purchase and the nature of the damp, one or more legal routes may be available to you.
Misrepresentation by the seller. When completing the Property Information Form (TA6), the seller must answer honestly about damp and flooding. If the seller knew about a significant damp problem and answered “no” or “not known” to the relevant questions, this may constitute misrepresentation. If the seller had the property freshly decorated immediately before sale specifically to conceal visible damp evidence, this is a more serious form of active misrepresentation.
Misrepresentation claims are not straightforward — you must prove the seller knew about the problem and made a false representation. Evidence that supports a claim includes:
- The survey report that shows elevated moisture consistent with a long-standing problem, not a recent event
- Thermal imaging showing evidence of fresh decoration applied over a moisture-affected surface
- Neighbours, previous estate agent particulars, or local knowledge that the property was known to have a damp problem
- Any written communication from before exchange that touched on the condition of the property
A solicitor with experience in property misrepresentation claims — not your conveyancing solicitor — should review the evidence. Initial consultations are often free or low-cost.
Negligent surveyor. If you commissioned a RICS Level 2 or Level 3 survey and the surveyor failed to identify damp that was present and accessible at the time of the survey, you may have a claim against the surveyor for negligence. The standard of care is whether a competent surveyor exercising reasonable skill and care would have identified the problem.
Surveyors are not infallible — surveys are visual inspections with limited instrument use and do not access concealed areas. But there is a difference between damp behind a false ceiling that no inspection could have found and a large damp patch on an accessible wall that was directly in front of the surveyor. Obtain a second professional opinion on whether the damp was reasonably identifiable at the time of survey.
RICS surveyors carry professional indemnity insurance specifically to cover negligence claims. The claim is typically submitted to the surveyor’s insurer rather than pursued through litigation initially.
Buildings insurance. Buildings insurance covers sudden and unforeseen damage — not pre-existing conditions. A damp problem that has been developing for years is not typically an insured event. However, if the damp is caused by a specific insured peril — a burst pipe that occurred after completion, a storm event, a failure in the roof that allowed water ingress — your buildings insurance may cover the damage and the remediation.
Notify your insurer of any potential claim as soon as the damp is discovered — even before the cause is established. Getting a claim reference number early preserves your position.
Home buyer’s protection insurance. Some buyers purchase RICS-endorsed home buyer’s protection insurance before a purchase that specifically covers the costs of abortive transaction costs if the sale falls through — but this does not cover post-completion defects.
New build warranty (NHBC, Premier, LABC). If the property was a new build, a new build warranty — most commonly NHBC Buildmark — covers major structural defects for 10 years from the date of build. If the damp is related to a structural defect in a new build within this period, the warranty claim route is available.
Step 4 — Engage a Solicitor Before Doing Anything Irreversible
If you believe the damp was undisclosed or that a legal claim may be available, seek legal advice from a property litigation or misrepresentation specialist before carrying out any major remediation work.
There are two reasons for this.
First, extensive remediation before a legal claim is established can be characterised as you having accepted the condition of the property. This does not automatically kill a claim, but it can complicate the evidence picture.
Second, if the claim involves asserting that fresh decoration was applied over pre-existing damp, you need the thermal imaging and moisture evidence captured before the surfaces are stripped or treated. Once the affected plaster is removed and the walls are dried and replastered, the physical evidence of the original condition is gone.
The practical instruction is: document everything, commission the moisture survey, and then seek legal advice before instructing any contractor for major remediation.
For guidance on the misrepresentation act and property purchase disputes, check: Citizens Advice — problems when buying a home
Step 5 — The Remediation Programme
Once the legal position is established and any professional advice about preservation of evidence is followed, the practical programme of drying and restoring the property can begin in full.
For condensation: Ventilation improvement first — bathroom and kitchen extract fans venting externally, trickle vents, and if necessary Positive Input Ventilation. Industrial desiccant dehumidification to manage ambient humidity during the drying period. Professional mould treatment if mould is established.
For penetrating damp: Identify and repair all external defects. Then industrial drying of the affected masonry and fabric. Replaster with appropriate specification once dry standard is confirmed.
For rising damp: Professional DPC assessment and treatment — either chemical injection or confirmation that the existing DPC simply needs the external ground level lowered to remove the bridging. Remove salt-contaminated plaster and replace with specialist renovating plaster after the fabric reaches dry standard.
For post-flood moisture: BDMA-certified drying programme with industrial desiccant equipment, daily monitoring, and confirmed dry-standard certification before any reinstatement.
In all cases, replastering and redecorating must wait until calibrated moisture metre readings across all affected surfaces are stable at the dry standard — not at a specific number of weeks, not when the walls feel dry to touch, but when instruments confirm confirmed equilibrium.
Disaster Care Capital provides the full service for newly purchased properties with damp — the professional moisture survey that establishes the evidence baseline, the drying programme, and the drying certificate that supports any insurance claim or legal case. We work directly with solicitors, loss adjusters, and insurers. Call us today for a free same-day assessment.
For RICS guidance on surveyor negligence and complaints, check: RICS — complaints and dispute resolution
Conclusion
Damp discovered in a newly purchased house is a serious problem — but your options are not limited to accepting it and spending your own money on remediation. Document immediately, commission a specialist moisture survey, and then assess each of the three legal routes — seller misrepresentation, surveyor negligence, and buildings insurance — before making any irreversible decisions about remediation. The moisture survey is the evidence document that underpins every subsequent step. Get it first.
Frequently Asked Questions
Can I claim against the seller for damp in a house I just bought?
Potentially yes — if the seller knew about the damp and made a false representation on the Property Information Form, or if active steps were taken to conceal the problem (such as fresh decoration over visible damp). A BDMA moisture survey report establishing the extent and probable duration of the problem, combined with thermal imaging evidence of any concealed damp, is the evidence needed to assess the viability of a misrepresentation claim.
Can I claim on my survey if the surveyor missed damp?
Potentially yes — if the damp was present and accessible at the time of the survey and a competent surveyor exercising reasonable skill would have identified it. Obtain an independent professional opinion on whether the damp was reasonably identifiable before pursuing a negligence claim against the surveyor. RICS surveyors carry professional indemnity insurance specifically for this purpose.
Does buildings insurance cover pre-existing damp?
Generally no — buildings insurance covers sudden and unforeseen events, not pre-existing conditions. However, if the damp is caused by a specific insured event that occurred after completion (a burst pipe, a storm-related roof failure), an insurance claim may be viable. Notify your insurer immediately when damp is discovered to preserve your position.
What should I do first if I discover damp in a newly purchased property?
Document everything with timestamped photographs before touching, moving, or remedying anything. Note any signs of recent decoration over affected areas. Then commission a BDMA-certified moisture survey — this establishes the professional evidence baseline for every subsequent option, whether legal, insurance, or practical remediation. Seek legal advice before instructing major remediation if a seller misrepresentation or surveyor negligence claim may be available.